
Farrsal
Financial news and analysis

Global insights for better decisions.

Economic, market and geopolitical coverage with clear context.

FarrsalNews for a Smarter Tomorrow
Financial news and analysis•4 min readPage 2 of 3

O'Leary's New Ryanair Deal Could Be Worth Over €150 Million – Here's the Fine Print

Ryanair’s board has approved a new contract for CEO Michael O’Leary that could be worth over €150 million, extending his tenure until 2032 and introducing a bon…

Farrsal Editorial
Farrsal · News for a Smarter Tomorrow
f𝕏WAin
O'Leary's New Ryanair Deal Could Be Worth Over €150 Million – Here's the Fine Print
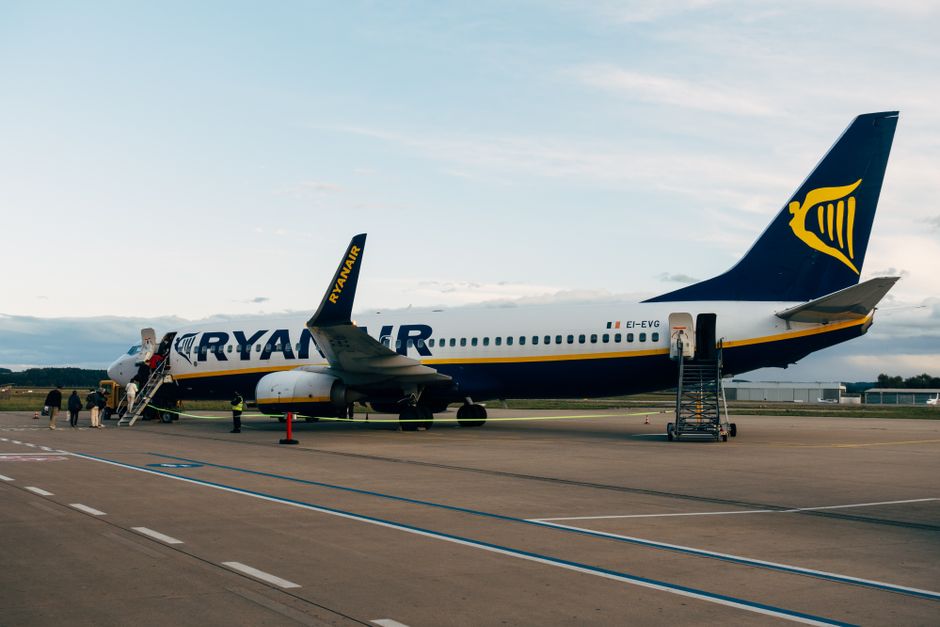
Article image: O'Leary's New Ryanair Deal Could Be Worth Over €150 Million – Here's the Fine Print

Article Highlights

Excerpts from the article

  • Ryanair’s board has approved a new contract for CEO Michael O’Leary that could be worth over €150 million, extending his tenure until 2032 and…
  • Michael O’Leary has led Ryanair since 1994, transforming it from a regional carrier into Europe’s largest low-cost airline by passenger numbers.…
  • His previous bonus plan, adopted in 2018, awards roughly €100 million if Ryanair’s stock averages above €21 for 28 consecutive trading days before…

The options only vest if Ryanair achieves either a €4 billion annual after-tax profit or a 28-day average share price above €42. Both thresholds are far above current performance: Ryanair’s record profit of €2.26 billion in fiscal 2024 is roughly half the required level, while its stock has never reached €42. The options expire in 2032, giving O’Leary seven years to hit the targets. If neither condition is met, the options become worthless.

Industry analysts note that the €4 billion profit target implies a doubling of earnings, which would require sustained low fuel costs, higher passenger yields, and no major disruptions. Ryanair has forecast traffic of 205 million passengers in fiscal 2025, up from 184 million in 2024, but faces headwinds from Boeing’s delivery delays — which have slowed fleet expansion — and rising competition from Wizz Air and other budget carriers.

⚠️ Analyst view, unconfirmed: The €42 share price target is 120% above current levels, and achieving it would require a market cap increase of roughly €10 billion. Some investors question whether such aggressive growth is realistic given the airline industry’s cyclicality.

Market Reaction and Governance Concerns